Back to storiesSale and purchase
Upside down on the old house and still getting the new one: a Conroe buyer story
4 min read By Deborah Rose Miller, Deborah Rose Real Estate Group Conroe, Texas
The numbers
- Sold price
- $455,000
- Home
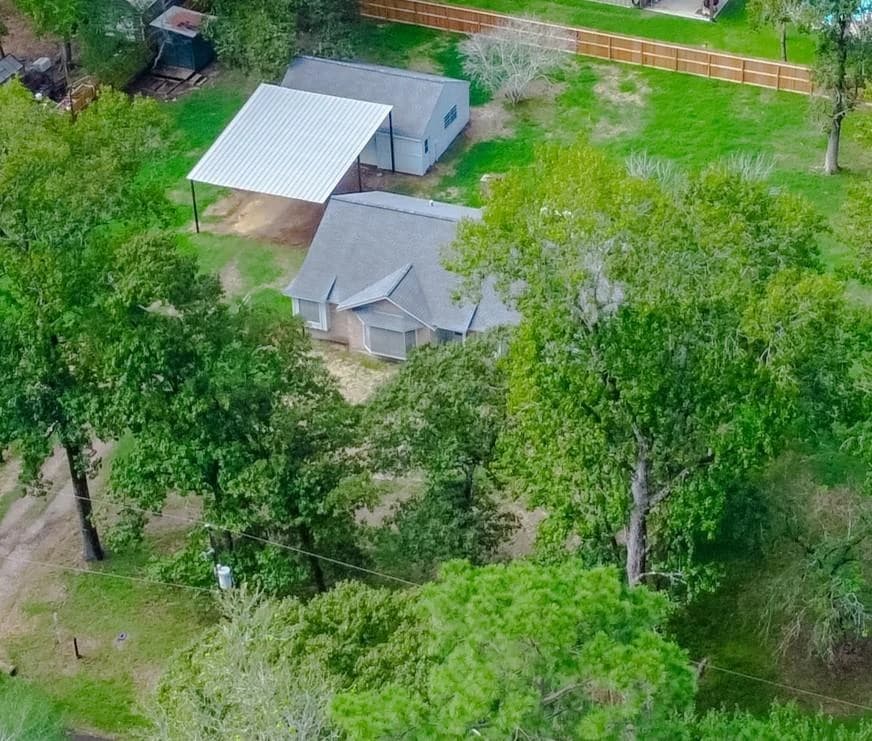
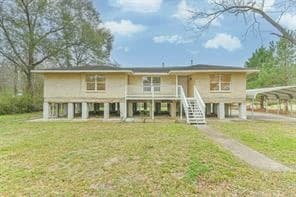
- 3 bed, 2 bath, 1,644 sq ft on acreage
- Area
- Southeast Conroe, 77302
- Closed
- April 2026
Some transactions test every tool in the box, and this one, in the Conroe area of Montgomery County, is a good example of why creative problem-solving matters as much as market knowledge.
The situation
I was working with a young couple with three children who had found their dream home. They knew exactly which part of Conroe they wanted to be in, a specific acreage property on the southeast side, and they were ready to move.
The problem was the house they already owned. They were upside down on it, meaning they owed more on the mortgage than the home was worth on the current market. That is a tough spot under any circumstances. It is especially tough when you have already found the home you want to buy next and the clock is ticking.
Why the standard playbook fails here
Being upside down on a home you need to sell before you can buy again closes off most of the usual options. You cannot list it, wait for full asking price, and roll the proceeds into your next down payment, because there may not be meaningful proceeds to roll. Traditional buyers looking at that property were never going to solve the timing or the numbers problem this family needed solved.
So instead of forcing a conventional sale to a conventional buyer, I went a different direction. I brought in an investor who was willing to work with the numbers as they actually stood.
Breaking even
That investor purchase did not make this family any money on their old house. It came nowhere near what they might have hoped for in a better market. What it did was let them break even: walk away from the existing property without taking on additional debt, and without paying two mortgages for months while they waited for a traditional buyer who might never materialize at the price they needed.
Breaking even is not a headline number. When you are upside down and trying to move a family of five into a new home, breaking even instead of losing money is the difference between the deal happening and the deal falling apart.
Closing the gap
With that piece solved, the family still needed to cover the gap to afford the home they wanted in Conroe. This is where their relatives stepped in. With some family help, they were able to put together what they needed.
I want to be clear about my role in that part. I did not arrange the family assistance, and I could not have. What I did do was structure the rest of the transaction, the timing, the contingencies, the paperwork and the communication with every party, so that once the family had what they needed, nothing on my end slowed things down or put the deal at risk. The closing date moved twice, the appraisal came in at value with one repair item, a piece of rotten wood, and we closed at the end of April.
What made it work
It was not one clever move. It was refusing to treat "you are upside down on your current house" as a dead end, and instead breaking the problem into pieces that could each be solved on its own.
Solve the old house first, even if the outcome there is modest. Keep the family's eyes on the actual goal, which was never about maximizing profit on the sale of a starter home. It was about getting their family into the home that fit them. And stay flexible about who the buyer for that old property might be, because sometimes the right buyer is an investor who can move fast and work within numbers a traditional buyer cannot.
This family ended up in the home they wanted, on the land they wanted, in the part of Conroe they had set their sights on. Watching a young family with three children reach that finish line after starting out underwater on their mortgage is the kind of outcome that makes this work worthwhile.
If you feel stuck
Being upside down does not automatically mean you are stuck. It means the path forward is probably not the standard one, and you need someone willing to look at unconventional options: investor sales, creative timing, contingencies structured carefully. The numbers on your current house are one part of the equation. The other part is figuring out every possible way to get you to the next one.
If you are feeling boxed in by your current mortgage but you already know the home or the neighborhood you want next in Conroe or anywhere in Montgomery County, let's talk. I would rather look at three unconventional options with you than tell you it cannot be done.